A Rolex collateral loan is a loan secured by your watch. The lender evaluates the watch, offers terms based on its resale and collateral value, and keeps it in secure storage while the loan is outstanding. If you repay the amount due under your agreement, you generally get the same watch back. If you do not repay on time—or do not follow the agreement’s renewal or extension rules—the lender may have the right to sell it.
That sounds straightforward, but the details matter. Before handing over an inherited or personally meaningful watch, understand how it will be authenticated, how the loan and fees are calculated, where the watch will be stored, and exactly what happens if you need more time. A watch collateral loan is not the same as selling your Rolex, and “I can get it back later” is only true if you meet the contract’s terms.
How a Rolex collateral loan usually works
You bring in the watch for evaluation. The lender examines its condition, authenticity indicators, completeness, and likely resale market. You may be asked about its history and where it has been stored—such as in a safe, a dresser, or a coffee can. Storage history does not authenticate a watch, but it can help explain its condition and any concerns. The lender makes an offer. The offer is based on the lender’s assessment of the watch as collateral, not simply its original retail price or the amount you hope to borrow. The amount offered may be lower than what you could receive through a carefully managed private sale. You review and sign the agreement. Check the loan amount, interest, other fees, due date, renewal or extension options, and consequences of late or missed payment. Ask whether you can repay early and whether any charges still apply. The watch is held during the loan. The lender should explain how the watch is documented, protected, and stored. Ask about secure storage, insurance, access controls, and how the watch will be identified when it is returned. You repay according to the contract. Once you satisfy the amount due and any required procedures, the lender releases the watch to you. Keep your payment records and get a receipt when you collect it.Providers differ in how they assess watches and structure loans. A company such as Diamond Banc may offer a collateral-loan process, but do not assume that any lender has the same rates, deadlines, storage arrangements, or extension policies. Get the specific terms in writing before you leave your Rolex.

Do you get your Rolex back?
Usually, you can repay the loan and get your watch back—but only if you meet the agreement’s requirements. Read the contract for the exact payoff amount and deadline. A quoted loan amount is not necessarily the full amount you will owe. Interest and fees may accrue, and an extension may require a payment or a new agreement.
If you miss the deadline, the outcome depends on the contract and applicable law. The lender may have the right to take ownership or sell the watch after any required notices or waiting period. Do not rely on a verbal assurance that “we can work something out.” If you think you may need additional time, ask about the process before signing and get any extension confirmed in writing.
Before agreeing, ask these direct questions:
- What is the total amount I must pay to retrieve the watch, and by what date? What interest, storage, service, or administrative fees can apply? Can I renew or extend the loan? What does that cost, and how early must I request it? What happens if I pay late or cannot repay? How is the watch insured while in your possession, and what does that coverage exclude? Will the watch remain in the same condition, and will it be handled, wound, or serviced? What identification or paperwork will I need when I collect it?
If losing the watch would cause serious financial or emotional harm, consider whether selling it, borrowing another way, or not borrowing may be safer. A loan can provide short-term cash, but it also creates a deadline tied to an item you may not be able to replace.
Why a home authenticity test is not enough
Online videos and kitchen-table tests can be useful for learning what to look at, but they cannot reliably authenticate every Rolex. Weight, a moving seconds hand, a familiar sound, a logo, or a magnified view of one detail is not a verdict. Parts can be replaced, watches can be assembled from mixed components, and convincing counterfeits can imitate visible features. Some genuine watches also have service parts or wear that looks unusual to a non-specialist.
A responsible evaluation considers the watch as a whole. Depending on the watch and the situation, that may include examining the case, dial, hands, bracelet, movement, markings, and signs of prior repair. Opening a watch is not something to attempt casually: improper handling can damage components or compromise water resistance. A lender may also distinguish between a watch that appears genuine and one whose components, condition, or service history support a particular valuation.
Do not polish a case, replace a dial, or arrange repairs just to make the watch look newer before an evaluation. Polishing can remove material and soften original edges; replacement parts may affect collector interest. Ask for an evaluation before authorizing cosmetic work. An appraiser can tell you whether a repair is advisable and whether it should be documented.
Modern and vintage Rolex identification pitfalls
Modern watches
Newer Rolex watches commonly have a warranty card that is credit-card-sized. The card can help identify details associated with the original sale, but it does not, by itself, prove that the watch currently presented with it is genuine or that every component is original. Cards can be separated from watches, and documents can be altered or mismatched. The watch and its identifying details still need to be examined.
Older watches
Older watches may come with paper certificates rather than a modern card. Paper can be fragile, incomplete, or absent, and its presence is not a substitute for examining the watch. Vintage identification can be especially complicated because watches may have been serviced over many decades. A dial, hands, bracelet, or movement component may have been replaced, and a later service part can be legitimate without being original to the watch as first sold.
That is why a https://www.sandiegoreader.com/contributor/readernews/the-rolex-in-the-junk-drawer/ single detail—whether it looks old, has a certificate, or has a certain style of marking—should not decide authenticity or value. Vintage evaluation often requires weighing originality, service history, condition, and the watch’s documented identity together. The standards and market preferences for older pieces may differ from those for modern watches.
Reference and serial numbers: what they unlock
Reference and serial numbers can help an evaluator narrow down a watch’s identity and research its production period, configuration, and market context. They can also help compare the watch with records, paperwork, and other examples. In that sense, the numbers unlock better questions: Does the configuration make sense for the watch? Do the accompanying documents correspond? Are the visible parts consistent with the identification?
They are not a magic authenticity stamp. Numbers may be difficult to read, may have been altered, or may not settle whether a particular component is original. A number alone also does not establish current condition or resale value. An evaluator interprets it alongside the physical watch and supporting documentation.
For privacy and security, avoid posting clear photographs of identifying numbers online. Share them with a qualified professional or lender when needed for an evaluation, and ask how the information will be recorded and protected.
What box and papers can—and cannot—do
A matching box, warranty card or older paper certificate, booklets, tags, and service records can make a watch more complete and may improve buyer confidence. In some cases, completeness can support stronger resale interest. But the effect depends on the watch, the documents, their consistency, and the market. A box is not proof of authenticity, and papers do not turn a questionable watch into a genuine one.
The reverse is also important: no papers does not mean the watch is worthless. Many legitimate watches have been separated from their paperwork over time, especially inherited or pre-owned pieces. A lender may still evaluate the watch itself. Missing documents can affect confidence or an offer, but they are only one part of the assessment.
Item What it may help with What it does not prove Modern warranty card May provide identifying or sale-related information That the card belongs to the watch or that every component is authentic Older paper certificate May support the watch’s history or original documentation That the watch has remained unchanged or is authentic today Box and accessories Can add completeness and buyer appeal Authenticity or a guaranteed increase in loan value Reference and serial numbers Help with identification and research Condition, originality of every part, or a guaranteed loan amountHow a lender decides what to offer
A collateral lender is assessing the watch as security for a loan, not conducting a sentimental appraisal. Factors may include authenticity, condition, demand, completeness, service needs, and how readily the watch could be resold if the loan is not repaid. The lender’s offer can differ from an insurance replacement estimate, an auction result, or a private-sale price because each figure answers a different question.
Do not expect a precise figure from generic online information. A meaningful evaluation requires the actual watch and its documentation. No specific Rolex model names, reference numbers, or dollar prices are supplied here, so none should be inferred or invented. If a lender gives an offer, ask what it is based on and whether the amount assumes the watch is in its current condition.
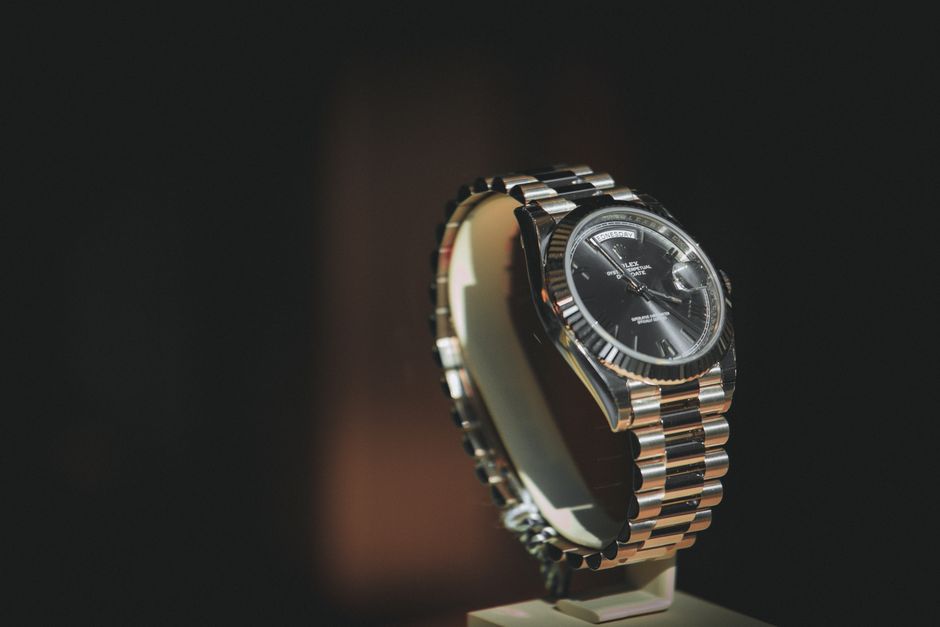
How to prepare before you take it in
- Gather any warranty card, older paper certificates, box, tags, receipts, and service records you already have. Do not assume you need to buy missing accessories. Bring the watch as it is. Avoid polishing, opening, or making undocumented changes before an evaluation. Be ready to describe what you know about its history, including where it was stored. If it was inherited, say what is known and what is not. Ask for the proposed loan terms in writing and take time to read them. Confirm how the watch will be photographed, logged, insured, and kept in secure storage. Keep copies of the signed agreement and any intake paperwork, and photograph the watch’s condition before leaving it. Do not hand over a watch if you cannot explain how to repay or what happens if you cannot.
Is a collateral loan right for you?
A Rolex collateral loan may suit someone who needs temporary cash and has a credible plan to repay on time. It can be an alternative to selling, because repayment may allow the owner to recover the watch. But the loan is not risk-free: the watch is tied to the debt, and failure to meet the contract can mean losing it.
San Diego readers researching local options may come across coverage and discussion in the San Diego Reader. Treat articles, online estimates, and general advice as starting points, not substitutes for reading a lender’s current contract or getting the watch evaluated in person.
The practical answer to “do I get it back?” is: you can get it back if you repay the loan and satisfy the agreement’s requirements before the applicable deadline. Confirm the payoff, fees, extension rules, and secure-storage arrangements in writing. And remember that authentication is more than a home test, paperwork is supporting evidence rather than a guarantee, and a missing box or certificate does not make a Rolex worthless.